October saw Indian startups secure $678 million in funding, down 47.5% from September, with the lack of major funding rounds contributing to the slowdown in overall investments. Fairfax agreed to buy 60.72% of IDBI Bank for ₹52,877 crore, Jio Platforms raised ₹30,213 crore in the biggest IPO of the month, and Tata Motors secured 89% of Iveco. Startup funding, meanwhile, fell to $678 million, roughly half of September’s total.
This is the second edition of our monthly series on the deals shaping India’s business landscape. Each month we go through the funding rounds, acquisitions and exits announced across India and explain what they mean for business owners, investors and anyone looking to buy a business. Every company name below links to the report we took the details from.
October in 60 seconds
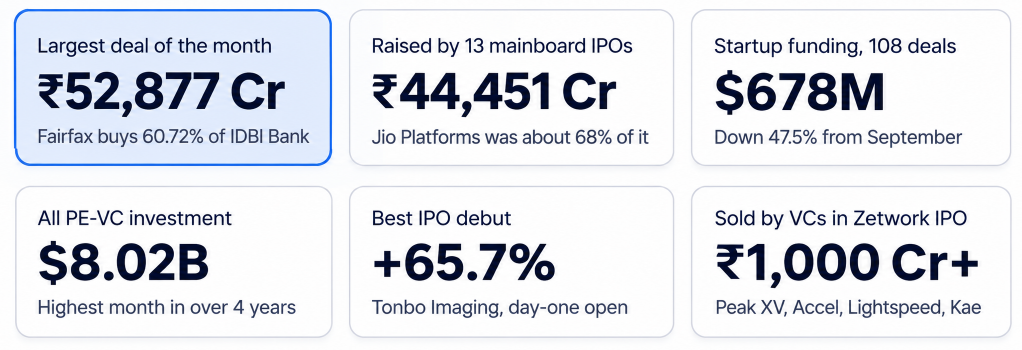
If you only have a minute, these numbers tells the story of the month. The details and source links follow below.
- Startup funding: $678 million across 108 deals, down 47.5% from September. No startup raised $100 million or more.
- All PE-VC investment: $8.02 billion across 106 deals, the highest monthly total in over four years. About 70% of that is the IDBI Bank deal.
- Biggest acquisition: Fairfax Financial agreed to buy 60.72% of IDBI Bank for ₹52,877 crore.
- Biggest fundraise: Persistent Systems raised ₹4,265 crore through a QIP. The largest startup round was Tessolve Semiconductor’s $75 million.
- IPOs: 13 mainboard IPOs raised ₹44,451 crore. Jio Platforms accounted for about 68% of that.
- Best debut: Tonbo Imaging opened 66% above its issue price. Jio Platforms listed 21% higher.
- Investors cashing out: VCs sold over ₹1,000 crore of shares in Zetwerk’s IPO, and Tencent sold ₹982 crore of Swiggy stock in a block deal.
How October compares with September
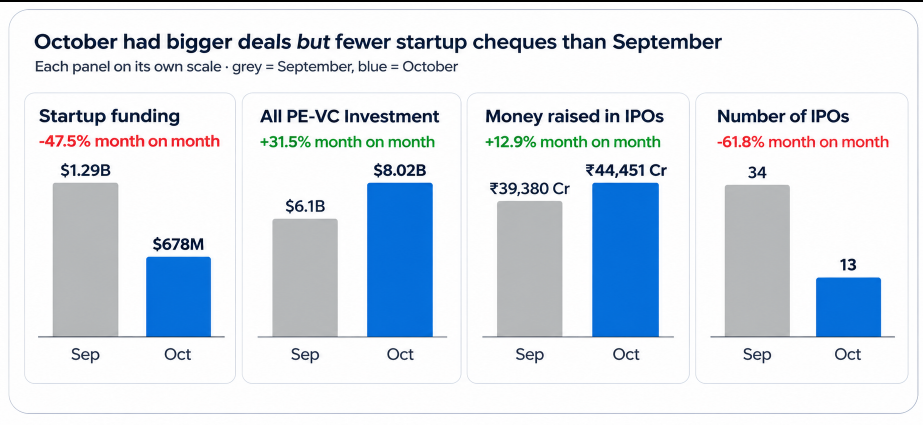
Set side by side, the two months tell different stories. Startup funding almost halved, while total PE-VC money and IPO proceeds went up, carried by two very large deals: IDBI Bank and Jio Platforms.
Top highlights of the month: 10 deals that moved the needle
These are the ten largest transactions of October across M&A, IPOs, block deals and fundraises, ranked by size. Two deals stand far above the rest: a foreign takeover of a listed bank and India’s biggest IPO of the month.
| No. | Deal | Type | Size |
| 1 | Fairfax buys 60.72% of IDBI Bank | Inbound acquisition | ₹52,877 Cr |
| 2 | Tata Motors’ Iveco offer crosses 89% | Outbound acquisition | ~€3.43B |
| 3 | Jio Platforms IPO | IPO (all fresh issue) | ₹30,213 Cr |
| 4 | ITC block deal | Block deal (~2.9%) | ₹9,437 Cr |
| 5 | Zetwerk IPO | IPO | ₹5,012 Cr |
| 6 | Persistent Systems QIP | Fundraise | ₹4,265 Cr |
| 7 | Bonfiglioli Transmissions IPO | IPO (all OFS) | ₹2,534 Cr |
| 8 | KPI Green buys Alfanar’s Gujarat wind portfolio | Acquisition | ~₹2,410 Cr EV |
| 9 | Sagility block deal | Block deal (11.96%) | ₹2,395 Cr |
| 10 | PTC Industries QIP | Fundraise | ~₹1,800 Cr |
Reading between the deals: three signals we would watch
1. Big-ticket money is flowing, but startups are getting fewer cheques. PE-VC investment hit $8 billion, yet startup funding halved and no startup raised $100 million. Investors are backing large, proven assets and being more careful with young companies.
2. Jio Platforms set the tone for the IPO market. The ₹30,213 crore issue was 22 times subscribed and listed 21% higher. Smaller issues like Tonbo Imaging and HD Fire Protect also listed well above their issue price, so public markets are rewarding quality.
3. Global buyers want Indian assets. Fairfax (IDBI Bank), L’Oréal (Innovist), Embraer (Mahindra’s aerospace JV) and Nelnet (Entab) all bought into Indian businesses. For promoters with a strong brand, licence or technology, the buyer pool now includes serious foreign groups.
Big-ticket fundraises: listed companies had the easier month
Listed companies raised money much more easily than startups did this month. Three QIPs alone brought in about ₹7,465 crore.
- Persistent Systems raised ₹4,265 crore through a QIP between 21 and 26 October.
- PTC Industries raised about ₹1,800 crore through a QIP. Capital Group, Fidelity and HDFC MF were reported among the buyers.
- Cemindia Projects raised ₹1,400 crore through a QIP.
- Natco Pharma ran a ₹1,279 crore rights issue, and Ola Electric’s ₹1,000 crore rights issue opened on 22 October.
- MSME lender Vegafin raised up to ₹1,000 crore from Premji Invest, Norwest and Lok Capital. Part of the money funds a majority stake in Bizloan.
- OnEMI (Kissht) got exchange approval for an ₹832 crore preferential issue to mutual funds including Axis, HDFC and WhiteOak.
- Jio Allianz General Insurance raised ₹640 crore from its two parents. Ujjivan Small Finance Bank’s board approved ₹409 crore from IFC and insurers, and Norwest put ₹300 crore into SILA.
What it signals: Institutional investors have plenty of money for listed mid-caps with a growth plan. If your company is listed or heading that way, a QIP can be a faster route to growth capital than a private round.
IBGrid works with promoters, business owners and investors on business valuation, M&A advisory, fundraising and exit planning across India for fundraising & M&A deals for companies with annual turnover of INR 10 Cr to INR 200 Cr.
Startup funding: the growth-stage cheques
Thirteen startups raised $15 million or more, adding up to about $396 million. Hero Electronix-owned Tessolve Semiconductor led with $75 million, followed by Even Healthcare at $50 million and Boldfit at over ₹400 crore.
| Startup | Sector | Amount | Round | Lead investor(s) | Date |
|---|---|---|---|---|---|
| Tessolve Semiconductor | Semiconductors | $75M | Growth | Vector Line Capital, TPG | 12 Oct |
| Even Healthcare | Health insurance + care | $50M | Series B | Khosla Ventures | 19 Oct |
| Boldfit | Sportswear | ₹400+ Cr (~$42M) | Series B | Bharat Value Fund | 12 Oct |
| DailyObjects | Lifestyle accessories | ₹332 Cr (~$35M) | Series C | Xponentia, Anicut, Axiom Asia | 8 Oct |
| GreenCell Mobility | Electric buses | ₹330 Cr (~$35M) | Equity | Impact Fund Denmark | 13 Oct |
| RapidCanvas | AI | $29M | Series B | Vertex Ventures | 16 Oct |
| Scimplify | Specialty chemicals | $25M | Strategic | Hitachi Ventures | 14 Oct |
| AuxoAI | Enterprise AI | $20.7M | Series A | NTTVC | 21 Oct |
| Origin | Construction robotics | $20M | – | Accel, Zacua Ventures | 15 Oct |
| Navitas Solar | Solar manufacturing | Up to $20M | Growth | responsAbility | 22 Oct |
| Nat Habit | Ayurvedic personal care | ₹142 Cr (~$15M) | Series C | Trident Growth Partners | 12 Oct |
| Cent | Healthtech | $15M | Series A | Blume, South Park Commons | 27 Oct |
| Firstwork | HR tech | $15M | Series A | Earlybird | 23 Oct |
Glance also raised money from L Catterton on 26 October, but the amount wasn’t disclosed.
Startup funding: early-stage bets
We tracked 33 early-stage rounds between $4 million and $15 million, together worth about $300 million. AI infrastructure startup Simplismart led with $14 million, with NVIDIA among its investors. Green hydrogen firm Greenzo Energy and AI SaaS company Live2.ai raised ₹130 crore each.
| Startup | Sector | Amount | Round | Lead investor(s) | Date |
|---|---|---|---|---|---|
| Simplismart | AI infrastructure | $14M | Series B | Dallas Venture Capital, NVIDIA | 27 Oct |
| Greenzo Energy | Green hydrogen | ₹130 Cr | — | Ashish Kacholia | 20–23 Oct |
| Live2.ai | AI SaaS | ₹130 Cr | Pre-Series B | IvyCap Ventures | 27 Oct |
| Confido Health | Healthtech SaaS | $12.5M | Series A | Z47 | 15 Oct |
| Lumio | Consumer electronics | $12M | Series A | Blume | 7–8 Oct |
| Mesa School of Business | Education | ₹110 Cr | Series A (equity + debt) | Dharana, Elevation | 13 Oct |
| The Pant Project | Apparel | ₹109 Cr | Series B | Mirae Asset | 19 Oct |
| Beyond Appliances | Home appliances | ₹110 Cr | Series B | Fireside Ventures | 6 Oct |
| Spill Games | Gaming | $10.5M | Series A | Elevation Capital | 14 Oct |
| Troovy | Snacks | ₹100 Cr | Series B | Fireside, Sharrp | 27 Oct |
| Amaha | Mental health | ₹100 Cr | – | Lightbox, Fireside | 23 Oct |
| CureBay | Rural healthcare | ₹100 Cr | Pre-Series C | IvyCap Ventures | 22 Oct |
| Seeds Fincap | MSME lending | ₹100 Cr | Series B | Michael & Susan Dell Foundation | 1 Oct |
| StockGro | Investing platform | $10.4M | Series B | BITKRAFT | 6 Oct |
| Battery Smart | Battery swapping | ~₹98 Cr | Series C top-up | Ecosystem Integrity Fund | 17–20 Oct |
| Clueso | AI video | $10M | Series A | Dharana Capital | 13 Oct |
| Quanfluence | Photonic quantum | $10M | Series A | Chiratae Ventures | 7 Oct |
| Matiks | Social gaming | $10M | Pre-Series A | General Catalyst | 26 Oct |
| Ace Blend | Nutrition | $9.9M | Series A2 | 3one4 Capital | 29 Oct |
| MakeO (Toothsi) | Dental & skin care | ₹90 Cr | – | Singularity AMC | 13 Oct |
| byteXL | Edtech | $9M | – | Elevar Equity | 7 Oct |
| NeoGrowth | MSME lending | ₹85 Cr | Equity + debt | FMO, LeapFrog | 9 Oct |
| Rotoris | Luxury watches | ₹70 Cr | Series A | Blume | 27 Oct |
| Sunfox Technologies | Medtech | $7M | Series A | Ashish Kacholia, 3one4 + others | 7 Oct |
| Parallel Loop | Enterprise AI | $6.6M | Seed | 3one4 Capital | 14 Oct |
| Chapter Homes | Home & kitchen | ₹63 Cr | Equity + debt | Bessemer | 22 Oct |
| QpiAI | Quantum computing | ₹50 Cr | Venture debt | InnoVen Capital | 5–10 Oct |
| Shamrock AI | AI | $5M | Seed | Endiya Partners | 15 Oct |
| TravClan | Travel tech | $5M | Equity + debt | Flipkart | 22 Oct |
| CapGrid | Manufacturing | ₹46 Cr | Pre-Series B | Hero Enterprise | 16 Oct |
| Hunar AI | HR AI | ₹40 Cr | – | Blume | 19–20 Oct |
| Tradl | Fintech | $4.1M | Seed | Nexus, Stellaris | 26 Oct |
| NuSynth | Chemicals deeptech | ₹36.5 Cr | Seed | Avaana, Shastra VC | 13 Oct |
MoneyTruVa, Better Nutrition, RAAHO and CHOSEN also raised money in October without sharing the amounts.
What it signals: Investors are still backing early-stage companies with a clear use case: applied AI, quantum, healthtech and consumer brands with loyal buyers. Several rounds were led by individual investors like Ashish Kacholia, which shows HNIs are taking a more active role in early-stage deals.
Where the startup money went: AI takes the top spot
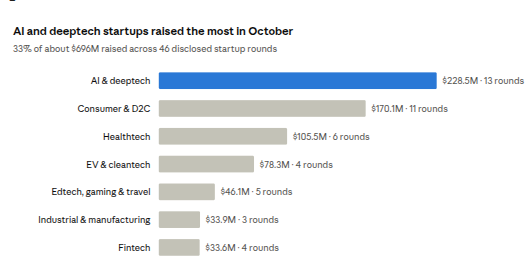
AI and deeptech took the lead this month, helped by Tessolve’s $75 million semiconductor round and a cluster of AI infrastructure and quantum deals. Consumer brands came second again, with Boldfit, DailyObjects and Nat Habit all raising growth rounds. EV and clean energy, September’s top sector, dropped to fourth with four rounds.
Mergers and acquisitions: The month foreign buyers came shopping
October had one very large deal, Fairfax-IDBI Bank, and a long list of mid-sized and smaller ones. The month stood out for foreign buyers: global groups bought into Indian banking, beauty, aerospace and software businesses. We’ve grouped the deals by who the buyer was.
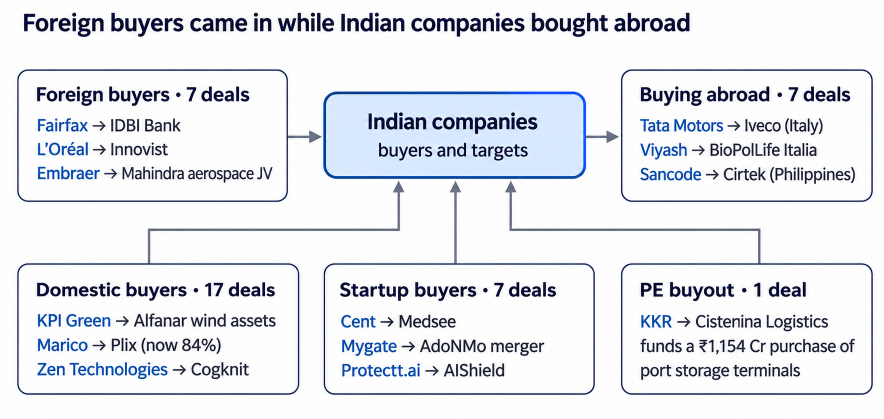
Foreign buyers of Indian businesses
Seven foreign groups bought into Indian businesses in October. The deals range from a ₹52,877 crore bank takeover to small software and testing companies, and most buyers wanted a licence, a brand or a ready team.
| Buyer | Target | Sector | Value | Stake |
| Fairfax Financial | IDBI Bank | Banking | ₹52,877 Cr (₹81/share) | 60.72% |
| L’Oréal India | Onesto Labs (Innovist) | Beauty D2C | Undisclosed | Majority |
| Embraer | Novavayu Aerospace (Mahindra) | Aerospace | Nominal (new JV company) | 51% |
| Nelnet Business Services | Entab Infotech | Edtech software | Undisclosed | – |
| Infotech (Info-Tech Research) | Zluri | SaaS | Undisclosed | 100% |
| SGS India | Prescient Cyber Audit & Assurance | Cyber audit | Undisclosed | – |
| IMPAG (Switzerland) | Broadways Chemtech | Chemicals | Undisclosed | – |
Indian companies buying abroad
Indian companies went overseas for technology and market access, mostly in Europe. Tata Motors’ Iveco offer is the headline, but mid-sized firms in animal health, semiconductors and medical devices also bought abroad.
| Buyer | Target | Sector | Value | Stake |
| Tata Motors | Iveco Group (Italy), offer result | Commercial vehicles | ~€3.43B | 89.42% tendered |
| Viyash Scientific | BioForLife Italia | Animal health | ~₹188 Cr | 100% |
| Sancode Semi | Cirtek Electronics (Philippines) | Semiconductors | $20.2M | – |
| Appasamy Associates | Ruck (Germany) | Ophthalmic devices | Undisclosed | – |
| Mapmygenome | dnaPower (Canada) | Genomics | Undisclosed | – |
| AXISCADES | Ulosia Holding AG | Engineering | Undisclosed | – |
| Univastu | Cambium Networks’ ePMP business | Telecom equipment | Undisclosed | Business |
Strategic buyers at home
Domestic deals made up the largest group, with 17 transactions. Renewables, consumer brands and financial services were the busiest areas, and several deals involved buying a specific asset rather than a whole company.
| Buyer | Target | Sector | Value | Stake |
| KPI Green Energy | Alfanar’s 508 MW Gujarat wind portfolio | Renewables | ~₹2,410 Cr EV | 100% |
| Marico | Satiya Nutraceuticals (Plix) | FMCG | ₹1,012 Cr | +24.09% (to 84.09%) |
| Mehul Shah + AIF | Great White Global (GreatWhite) | Consumer electricals | ~$91M (reported) | 50% |
| Runwal Group | NITCO’s Kanjurmarg land | Real estate | ₹143 Cr | Asset |
| Zen Technologies | Cogknit Semantics | Defence software | Up to ₹135 Cr | 51.98% |
| Auxilo Finserve | FinZ (PhysicsWallah) student-loan book | NBFC | ₹96 Cr | Loan book |
| Focus Prism | FoodExo | Catering | $15.8M | – |
| TCS | BBY Services India (Best Buy’s captive) | IT services | Nominal + ~₹2,000 Cr contract | – |
| Jagsonpal Pharma | Group Pharma’s wellness portfolio | Pharma | Undisclosed | Slump sale |
| Big FM | Sapphire Media’s news business | Media | Undisclosed | Business |
| Lloyds Metals & Energy | Three Amplus companies | Captive power | Undisclosed | 26%+ |
| ASK Asset Management | SageOne Investment Managers | Asset management | Undisclosed | – |
| Authum Investment + Inox Neo | Wind World (India), out of insolvency | Wind energy | Undisclosed | – |
| RR Kabel | U M Cables | Cables | Undisclosed | – |
| Lighthouse Learning | Pathways School Gurgaon | Education | Undisclosed | – |
| TreBits InvIT | Netria Property Holdings (from Trent) | Real estate | Undisclosed | 100% |
| Vegafin | Bizloan | NBFC | Undisclosed | Majority |
Private equity buyouts
Private equity was quiet on control deals this month. KKR’s majority investment in Cisternina, which is buying port storage terminals from Ganesh Benzoplast, was the one clear PE buyout.
| Buyer | Target | Sector | Value | Stake |
| KKR | Cisternina Logistics | Port logistics | Undisclosed (funds a ₹1,154 Cr asset purchase) | Majority |
Startups buying startups
Startup acquisitions were small and mostly about teams and technology. None of the seven disclosed a price, and healthtech and AI tools were the most common targets.
| Buyer | Target | Sector | Value |
| Mygate | AdOnMo (merger) | Adtech | Undisclosed |
| Cent | Medsee | Healthtech AI | Undisclosed |
| Hoola Health | UpTodd | Healthtech | Undisclosed |
| Leadrat | Calllive.ai | AI voice | Undisclosed |
| Protectt.ai | AIShield (from Bosch) | Cybersecurity | Undisclosed |
| Freshworks | Robusta (Israel) | SaaS / AI | Undisclosed |
| Liqvd Digital | Adlift Marketing | Marketing | Undisclosed |
Bigger deals that moved forward in October
- Tata Motors-Iveco: the offer crossed its 80% threshold with 89.42% of shares tendered. The first payment went out on 30 October, and the offer reopens briefly in November.
- Fairfax-IDBI Bank: Cabinet approved the sale on 14 October. An open offer and RBI approval are still pending, and the government defended its valuation on 30 October.
- Persistent Systems-Nagarro: The final takeover offer result came in at 94.04%.
- CCI approvals: on 30 October, CCI cleared Aditya Birla Renewables-Sprng Energy, Adani Energy Solutions–IntelliSmart and Prosus-Navi.
- Emirates NBD-RBL Bank: RBI approved the merger of Emirates NBD’s Indian branches into RBL Bank, effective 1 December.
- Indo Borax-Kronox Lab Sciences: the open offer for 25.79% at ₹157.27 a share ran from 15 to 29 October.
What it signals: foreign buyers are paying for things that take years to build in India, like a banking licence, a trusted beauty brand or a defence manufacturing partner. Domestic buyers picked up specific capabilities: wind assets, defence software, a school, a cable maker. If your business has a hard-to-copy asset, it may attract more potential buyers today than it did a year ago. Businesses considering a sale, acquisition or strategic partnership can benefit from professional M&A advisory services to navigate valuations, negotiations and deal execution.
IPO scorecard: Jio Platforms sets the tone
Thirteen mainboard IPOs raised ₹44,451 crore in October, up 12.9% from September even though there were far fewer issues. Jio Platforms accounted for about two-thirds of the total. The table covers IPOs that opened for bidding and listed in October.
The table below gives the issue size, listing date and who sold shares in each of these IPOs.
| Company | Issue size | Listed | Issue → listing price | Who sold shares |
|---|---|---|---|---|
| Jio Platforms | ₹30,213 Cr (all fresh) | 28 Oct | ₹1,119 → ₹1,358 | None (fresh issue); 22x subscribed |
| Zetwerk Manufacturing | ₹5,012 Cr (₹2,830 Cr fresh + ₹2,182 Cr OFS) | 23 Oct | ₹151 → ₹159.25 | Peak XV, Accel, Lightspeed, Kae Capital, founders |
| Bonfiglioli Transmissions | ₹2,534 Cr (all OFS) | 23 Oct | ₹586 → ₹586 | Italian parent (reported) |
| Paras Healthcare | ₹1,450 Cr (₹500 Cr fresh + ₹950 Cr OFS) | 28 Oct | ₹693 → ₹720 | Creador affiliate ₹650 Cr, promoter ₹300 Cr |
| Tonbo Imaging | ₹852 Cr (all OFS) | 23 Oct | ₹700 → ₹1,160 | Co-founders, Artiman Partners, CEAQ |
| HD Fire Protect | ₹712 Cr (all OFS) | 21 Oct | ₹271 → ₹335 | Promoters |
| Fusion CX | ₹702 Cr | 22 Oct | ₹289 → ₹305 | – |
| Sahajanand Medical Technologies | ₹476 Cr (all OFS) | 23 Oct | ₹344 → ₹371 | – |
Ten IPOs that listed in early October, including Moneyview, Orient Cables and AceVector, took bids in September and were covered in our September update. Five more issues opened in late October and list in November, so they’ll be in the next edition.
What it signals: Every IPO that opened in October listed at or above its issue price. Defence tech (Tonbo) and fire safety (HD Fire Protect) got the strongest response, so investors are paying up for niche businesses with a clear moat.
Who cashed out: Exits through block deals and IPOs
Block deals were dominated by large secondary sales in listed companies. ITC saw the biggest trade of the month, though the seller wasn’t identified. The clearer VC and PE exits came through the IPO market.
| Company | Seller | Stake sold | Size | Buyers | Date |
|---|---|---|---|---|---|
| ITC | Not identified | ~2.9% | ₹9,437 Cr | Not named | 8 Oct |
| Sagility | Sagility B.V. (promoter entity) | 11.96% | ₹2,395 Cr | Not named | 30 Oct |
| Lenskart | Alpha Wave (likely seller) | Up to 1.6% | Up to ~₹1,675 Cr | Not named | 12 Oct |
| Adani Ports | Not named | 0.3% | ₹1,234 Cr | Not named | 9 Oct |
| Swiggy | Tencent (per exchange data) | 1.87% | ₹982 Cr | SocGen, Morgan Stanley, Goldman Sachs, Nippon MF, ABSL MF | 30 Oct |
| GMR Airports | Not named | 0.87% | ~₹818 Cr | Not named | 9 Oct |
In the IPO market, Zetwerk’s offer for sale let Peak XV sell ₹359 crore, Accel and Lightspeed about ₹440 crore, and Kae Capital ₹196 crore of shares. In Paras Healthcare’s IPO, PE firm Creador sold ₹650 crore.
What it signals: The IPO route is working as a clean exit for VC- and PE-backed companies. Founders with institutional investors on their cap table can plan a listing as a realistic exit timeline, not just a hope.
Coming up: the IPO queue gets longer
The pipeline is getting deeper. IPO Guru counts 236 draft filings and 45 SEBI approvals in October across mainboard and SME issues. These are the ones worth tracking:
| Company | What happened | Date | Planned size |
|---|---|---|---|
| Carlsberg India | SEBI approval | 1 Oct | ~₹6,600 Cr, all OFS by the Danish parent |
| JSW One Platforms | Filed DRHP | 2 Oct | ₹3,054 Cr (₹1,300 Cr fresh + ₹1,754 Cr OFS) |
| Anarock Property Consultants | Filed DRHP | 1 Oct | ₹1,000 Cr (₹550 Cr fresh + ₹450 Cr OFS) |
| B.S. Sponge | Filed DRHP | 1–2 Oct | ₹1,000 Cr |
| Cult.fit | SEBI approval | 12 Oct | ₹950 Cr fresh + OFS (Temasek, Tata Digital, Accel among sellers) |
| Indian Gas Exchange | SEBI approval | 12 Oct | 1.67 Cr shares, all OFS by IEX |
| Paramotor Digital Technology | Updated DRHP | ~14 Oct | ₹1,000 Cr |
EAAA India Alternatives, SFC Environmental, BLS Polymers, M.K. Sons Fine Jewels and Bombay Coated & Special Steels opened in late October and list in early November.
What this means if you own or invest in a business
- If you’re a promoter thinking of selling: Both foreign and domestic strategic buyers were active in October. Most deals were mid-sized and aimed at a specific capability, like a wind portfolio, a defence software team, a brand or a school. For promoters considering a sale, understanding the m&a process and identifying what makes their business attractive to buyers can help them prepare for negotiations.
- If you’re raising growth capital: Startup funding halved from September and investors are writing smaller, more careful cheques. Profitable consumer brands, healthtech and applied AI still closed rounds. If you’re listed or close to it, QIPs are an open door right now.
- If you’re an HNI or family office investing directly: individual investors led several rounds this month, such as Ashish Kacholia in Greenzo Energy and Sunfox Technologies. Strong IPO debuts and active block deals also give you more ways to enter and exit.
- If you’re buying a business: Startups are picking up small AI and healthtech teams (Medsee, Calllive.ai, UpTodd), and listed mid-caps have fresh QIP money to spend. Expect more competition for good mid-sized targets in the months ahead.
Knowing what your business is worth is just as important before approaching potential buyers. Professional business valuation services can help promoters assess their company’s worth and enter negotiations with realistic expectations.
How did we put this together?
This update covers deals announced or completed in India between 1 and 31 October 2026. Every company name links to the report we took the details from, so you can check the numbers and read more. Amounts are shown as reported. For the Iveco ranking, we converted rupees to dollars at about ₹95 per dollar and to euros at about ₹110 per euro.
Different trackers count deals differently, so our totals won’t always match theirs exactly. We left out companies headquartered outside India, such as San Francisco-based Different and US-based BioStack, and talks that hadn’t turned into signed deals by month-end. Deals signed on 1 November, such as Affle’s acquisition of Perion, will be in the November edition. If we’ve missed a deal or got a detail wrong, write to us at [email protected] and we’ll update this page.
For business owners, this could be the time to understand what makes their company attractive to potential buyers. For investors and acquirers, identifying the right opportunity and assessing its strategic value remain equally important.
Whether you are planning a business exit, exploring an acquisition, evaluating a strategic partnership or preparing to raise growth capital, having the right transaction strategy can make a meaningful difference.
Planning your next business move? Connect with the IBGrid team to discuss your transaction objectives.
Missed our previous monthly update? Catch up on the September 2026 M&A, Funding & IPOs Update to explore the deals, investments and market developments that shaped the previous month.